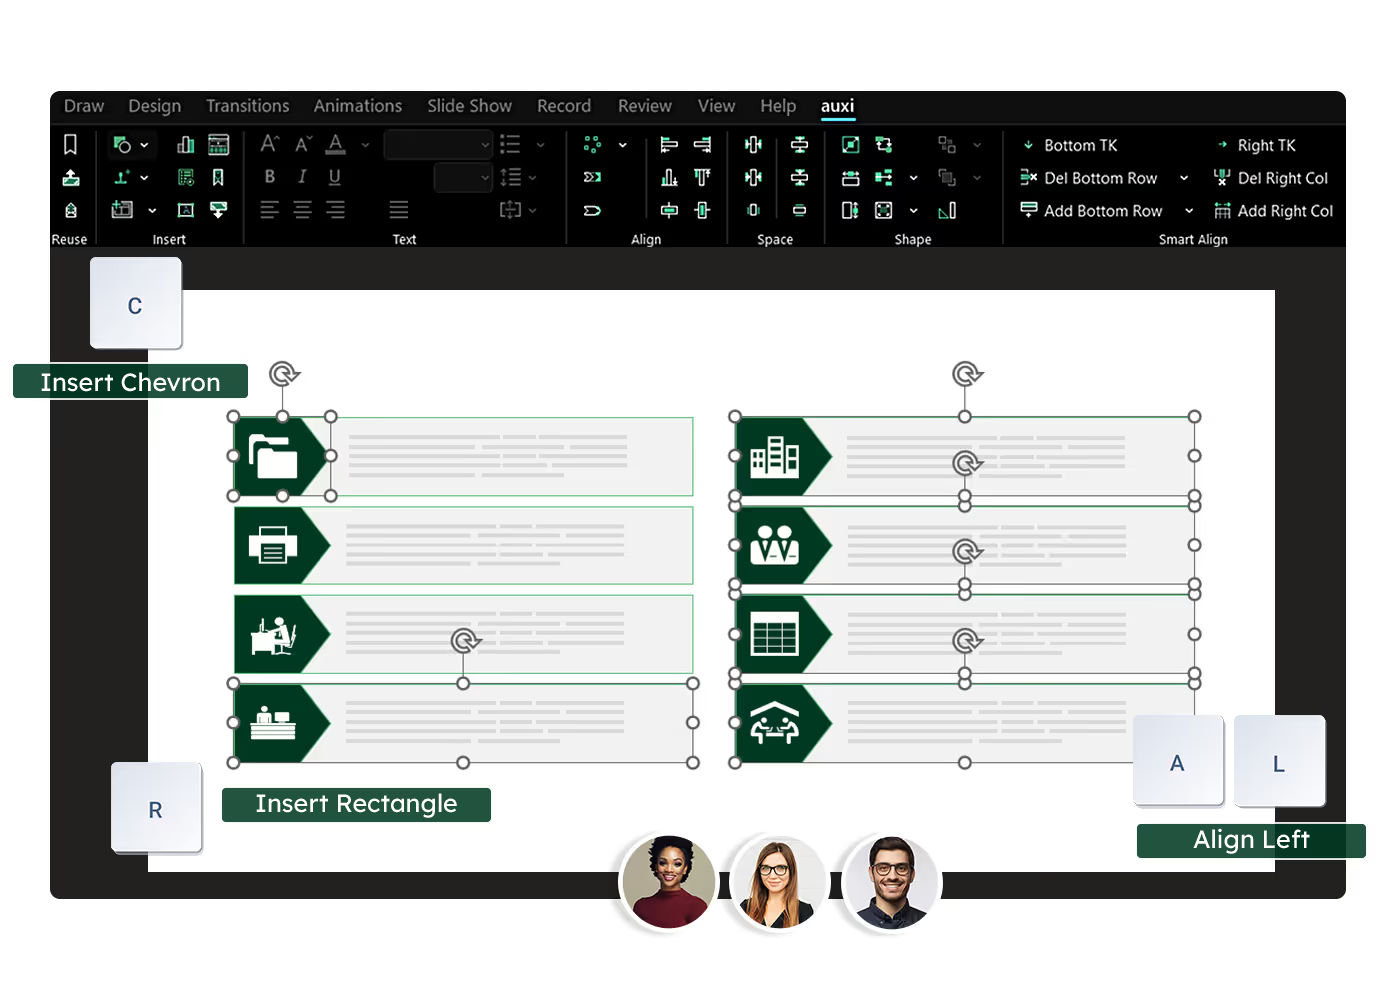
See auxi in action
your workflows and save you time!
An analyst finishes the first cut of a coverage pitch ahead of schedule. The associate sends it to the vice president, or VP, who asks for another valuation sensitivity. The managing director, or MD, adds a second prospect to the week's agenda. The analyst completes both and leaves at the usual hour.
The deal team may have gained productive capacity. The analyst may also have a valid concern about the workload. The group head needs to examine the additional work before deciding whether the bank used the gain well.
At auxi, we think an investment banking productivity discussion should follow the hours beyond the first draft. Track the effect on pitch volume and live execution, then ask the senior bankers how they want to allocate the capacity the team recovers.
Separate hours per pitch from hours per week
Consider a fictional team that spends ten hours preparing each of five pitches, for fifty hours of pitch production. After adopting a tool, the analysts and associates need seven hours per pitch. The coverage MD then asks the team to prepare eight pitches, taking total production effort to fifty-six hours.
The team produces 60% more pitches while spending six additional hours on them, despite a 30% reduction in effort per pitch. Assume the same scope and quality for this example. The VP would need to check both in a real evaluation.
Three additional pitches might give the MD access to promising mandates. They might also consume time the associate needed to review materials for a live sell-side process. The group head should compare those uses before treating more pitchbooks as evidence of a better outcome.
The staffing constraint can sit at a different level of the deal team. Several analysts may have capacity while the associate responsible for checking the model and pages is committed to live execution. Count the review hours at each level before promising another client turnaround.
Distinguish coverage from live execution
A speculative coverage pitch and a live transaction have different consequences for delay. An MD can decide to defer a prospecting discussion. On a live mandate, the team may have agreed dates with the client and other advisers.
The VP should identify the purpose of an additional request. A valuation sensitivity that changes the client's view of price deserves different treatment from a cosmetic alternative for an early coverage conversation. Both require time, but the associate needs to know which one takes precedence.
Include the type of material in the workload record. Updating trading comparables for a pitch differs from reconciling figures across a financial model and management presentation. Comparing those tasks under a single average for slides produced can conceal the effort the team still has to supply.
Junior bankers in a public forum described senior bankers using faster production to request more pitches. Those accounts are unverified and do not establish a trend in banking hours. An eight-month study at one US technology company also observed employees taking on more work as they used AI. That finding gives banks a question to test in their own teams; it does not establish the result in investment banking.
Record the turns through the associate and VP
An analyst can save time assembling pages and spend it on additional comments. Record the turns with a short explanation of the change: a new assumption, a numerical correction, a revised client message or a presentation preference.
The associate should verify that the model outputs and the pages agree. The VP should review whether the valuation narrative supports the recommendation the MD plans to discuss. If an AI-assisted workflow changes the effort at either stage, include it in the same calculation as the analyst's production time.
Suppose the MD changes the proposed positioning and asks for a revised buyer universe. That is a substantive request. If the VP and MD give conflicting direction, the analyst needs the associate or VP to resolve it before producing several versions. Faster page production can make it easier for senior bankers to postpone that choice.
Agree on what must be complete for the material to go to the client. After the team reaches that standard, the senior reviewer should explain the benefit of another turn before asking the analyst to reopen the deck.
Follow additional pitches to the client discussion
Track the labor required for comparable pitches, the number of additional pursuits and the total hours worked by the team. Connect the additional coverage to client meetings and mandates over a period that reflects the origination cycle.
Separate opportunities the MD would have pursued from those the team added because preparation became easier. A mandate can depend on a relationship developed over years, so avoid attributing the win to AI because the pitch used an AI tool.
Review the figures alongside staffing and live deal activity. A quieter transaction period can make a tool look more effective at reducing working hours. An active process can absorb the same capacity without giving analysts an earlier finish.
Let the group head make the allocation explicit
The group head can reserve part of the gain for additional coverage and part for reducing recurring late work. The VP can protect time for live execution and make that priority clear to the associate coordinating the pages.
We build auxi to reduce the effort bankers spend producing presentations. During an evaluation, involve the analyst, the associate checking the work and the VP who owns the timetable. Bring the MD into the decision about the next use of the time. The team can then assess whether it improved origination coverage, protected execution capacity or reduced the workload, rather than inferring the answer from the speed of a first cut.